



How African credit rating agency can influence cost of capital
Why does the cost of borrowing for African countries depend not only on their debt burden but also on the assessment of credit risk? Can continental expertise help investors assess the risks of different economies more accurately? Under what conditions could the establishment of a domestic credit rating agency influence Africa’s access to capital? Read the TV BRICS report
-
Photo source: Jacob Wackerhausen / iStock
AfCRA: Africa establishes its own risk assessment infrastructure
In October 2026, the Africa Credit Rating Agency (AfCRA) was officially launched in Port Louis, the capital of Mauritius. The initiative, which the African Union (AU), the African Peer Review Mechanism (APRM) and their partners have been preparing for almost ten years, is designed to promote the development of credit expertise across the continent.
AfCRA is being established as an independent, private-sector-orientated commercial entity. The agency is intended to complement the existing credit rating system by providing analyses that take into account the specific characteristics of African economies. It is envisaged that the agency will rate sovereign and sub-national borrowers, financial institutions and companies. The effectiveness of this model will depend on the quality of its methodology, the availability of data and the trust of market participants.
The creation of the new agency addresses a long-standing problem on the continent: access to finance is determined not only by actual economic indicators but also by the extent to which investors have comprehensive information about the borrower, its obligations and its development prospects. If data is limited, inconsistent or insufficiently comparable, it is more difficult for lenders to distinguish between the risks posed by individual countries and companies.
However, the launch of AfCRA does not guarantee that borrowing costs will fall. The agency will need to develop and refine its methodology, build up a track record of rating decisions and gain the trust of market participants. The practical outcome will depend on the extent to which its ratings prove to be independent, well-founded and sought after by financial institutions.
How credit ratings affect borrowing costs
A credit rating helps investors assess the ability of a government or company to meet its debt obligations. It is taken into account when determining the terms of borrowing but does not in itself determine the cost of borrowing.
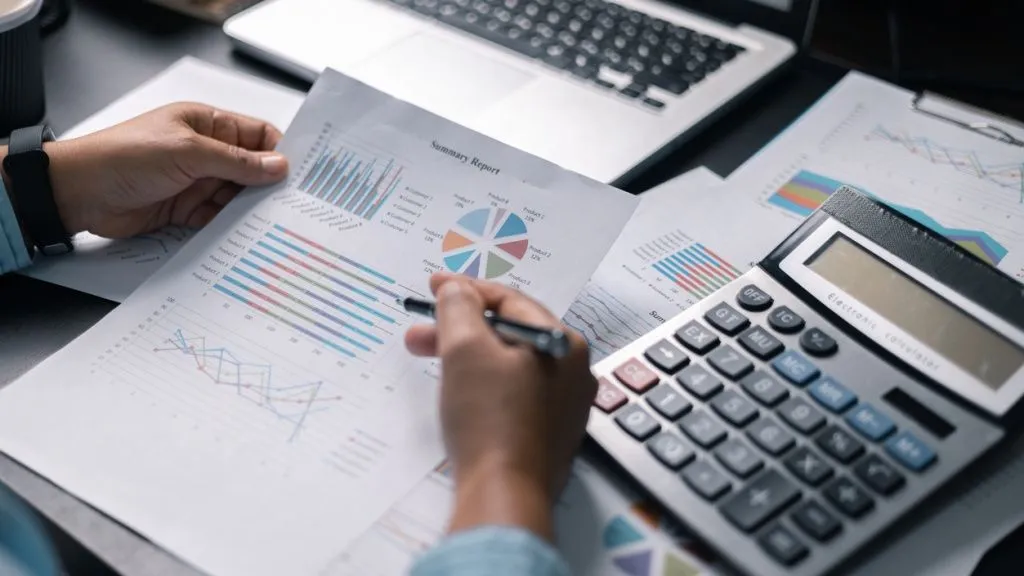 Photo source: Thai Noipho /
iStock
Borrowing conditions are also influenced by the level of public debt, the state of the budget, economic growth rates, currency risks and the volume of international reserves. Other factors include the currency in which bonds are issued, the maturity, market liquidity, current interest rates and investor demand.
Consequently, countries with comparable credit ratings may raise funds on different terms. A rating helps to assess a borrower’s creditworthiness but does not, in itself, determine the cost of borrowing.
For the Africa Credit Rating Agency (AfCRA), the development of creditworthiness assessments is important as a tool for improving the availability of information on borrowers. More comprehensive and comparable data can help investors make informed decisions; however, the final cost of financing still depends on a combination of economic and market factors.
AfCRA: how the new rating system works
The credit rating agency analyses the borrower’s financial position, its liabilities, sources of income and factors that may affect the fulfilment of its debt obligations. When analysing individual countries, the assessment focuses on fiscal sustainability, public debt trends, the ability to raise finance, external imbalances and the quality of economic governance.
For companies, other indicators are important: revenue, cash flows, debt burden, liability structure, asset quality and the ability to generate income. At the same time, corporate creditworthiness also depends on the external environment, including the state of the national economy, foreign exchange restrictions and the availability of finance.
 Photo source: Dragos Condrea /
iStock
The result of the analysis is a rating – an assessment of the borrower’s creditworthiness expressed on a standardised scale. The rating outlook reflects the expected direction of any potential change in the rating. A stable outlook means that, under current conditions, the agency does not expect the rating to change in the foreseeable future. Identical letter designations used by different agencies do not necessarily correspond to identical methodologies or risk levels.
AfCRA needs to establish a consistent rating practice. For market participants, the published ratings, the availability of methodological documents, the transparency of the reasoning, the regularity of reviews and the agency’s willingness to adjust ratings in response to changes in the borrower’s financial position will all be important factors.
Regional expertise can help to take into account the specific characteristics of African markets, including the structure of budget revenue, export specialisation and the availability of statistics. However, this advantage will only be of practical value if the local context complements a rigorous analysis of solvency, rather than serving as a basis for relaxing requirements on borrowers.
According to Zamokuhle Mbandlwa, a professor at Durban University of Technology, AfCRA should, in the initial phase, focus on those areas that address the most pressing challenges facing African financial markets.
"First, AfCRA should prioritise sovereign and corporate credit ratings. Sovereign ratings would help investors assess the creditworthiness of African governments, while corporate ratings would support the assessment of companies seeking loans, issuing bonds or attracting investment. Particular attention should be given to small and medium-sized enterprises (SMEs), infrastructure projects and businesses operating in sectors that are strategically important for African economic development," said Zamokuhle Mbandlwa, an expert in effective governance, ethical leadership and natural disaster risk management.
Credit ratings as financial market infrastructure
Credit ratings form part of a broader risk analysis system relied upon by banks, investment funds and insurance companies. When considering a transaction, an investor needs to assess the probability of default, the potential size of losses, the legal conditions for debt recovery and the liquidity of the instrument. A credit rating helps to organise some of this information, but does not replace an analysis of the terms of a specific transaction.
For investors operating across several African countries, the comparability of data on borrowers is important. Uniform disclosure requirements and a consistent methodology can simplify the analysis of different markets and reduce the costs of verifying data.
Ratings help to organise information about borrowers, but their practical value also depends on the extent to which market participants can consistently compare the ratings of different issuers.
Why financial integration requires comparable risk assessment
For investors operating across several African countries simultaneously, the comparability of borrower data reduces analysis costs and helps to identify differences in creditworthiness. However, a uniform methodology does not imply a one-size-fits-all approach to all economies: the assessment must take into account the structure of exports, the characteristics of the budgetary system, the exchange rate regime and the depth of the financial market.
A continental rating agency has the potential to expand the coverage of borrowers for whom limited analytical information is available and to provide an additional basis for comparing investment opportunities. But the comparability of ratings does not in itself guarantee an inflow of capital: an investor’s decision still depends on the borrower’s solvency, currency risks, the liquidity of the instrument and the terms of the specific transaction.
 Photo source: michaeljung /
iStock
According to Anna Krupina, an expert in Russian-African international relations, new rating agencies will have to strike a balance between applying their own methodology and integrating into the existing global rating system.
"For AfCRA not to be confined to local markets, it must ensure the international comparability of its assessments, secure recognition from foreign financial authorities, and have its ratings incorporated into the risk assessment procedures of international banks and investment funds. However, meeting these requirements does not guarantee international demand. It is precisely this understanding of the regional context for risk assessment, as well as the ability to provide the most comprehensive information on local borrowers, that represents analytical value. “Existing ratings cannot provide this when it comes to Africa," said Anna Krupina, an analyst at the Institute for the Development of Integration Processes of the All-Russian Academy of Foreign Trade (IRIP VAVT) under the Russian Ministry of Economic Development and a postgraduate student at the Institute of African Studies of the Russian Academy of Sciences.
Why AfCRA is important for BRICS and the Global South
The establishment of AfCRA is of interest to the countries of the Global South not merely as an African institutional initiative. BRICS is developing its own financial instruments and institutions, whilst the African Union is establishing a continental credit rating system. These are distinct processes that do not constitute a single rating system, but in both cases the issue of access to the financial instruments and professional expertise required for investment decisions comes to the fore.
The African continent is home to three full members of BRICS+: South Africa, Egypt, and Ethiopia. The economic conditions in these countries illustrate the different types of credit risk that a continental rating system must address.
 Photo source: Arnold Petersen /
iStock
South Africa serves as an example of a major financial market where, when assessing sovereign debt, it is necessary to take into account simultaneously its scale, the dynamics of the budget balance and the government’s ability to curb further growth in borrowing. Egypt illustrates just how significant the ratio of debt obligations, interest expenditure and international reserves is – that is, the balance between the scale of the debt and available external resources.
Ethiopia demonstrates another aspect of debt risk – the difficulty of restoring sustainable financing when debt restructuring is necessary. In 2025, the country concluded an agreement with official bilateral creditors providing for debt relief of more than US$3.5 billion. In 2026, the authorities announced that they had reached an agreement in principle with a group of international bondholders on the key financial terms of the restructuring; the completion of this process requires further negotiation.
These differences are important to AfCRA. The aim of the continental rating analysis is to identify more precisely the differences in the creditworthiness of borrowers with different economic models – rather than reducing them to a generalised view of the African market. Such expertise can be useful to investors operating across several African markets simultaneously, provided it allows for a more precise consideration of the differences between borrowers.
For other emerging economies, AfCRA’s experience could serve as a benchmark when establishing their own sources of credit analysis. However, this model can only be adapted to other regions by taking into account the specific regulatory frameworks, the structure of financial markets and investor requirements. The practical value of this approach will be demonstrated by the extent to which the new ratings are sought after by market participants.
The main risk is market confidence
AfCRA’s independence will be determined not only by its organisational status but also by its operational practices. It is important for the market that there are transparent rules for managing conflicts of interest and a willingness to publish assessments that may not align with the expectations of the countries and companies being rated. If the agency is perceived as a tool to shield African borrowers from negative ratings, this could undermine confidence in its ratings. Cases where the agency is forced to downgrade a country or a major company will be particularly telling.
Raymond Matlala, an expert in business, education and the Global South, believes that trust in the agency will depend not so much on its ownership structure as on its ability to demonstrate genuine institutional independence.
"AfCRA must establish strong governance mechanisms, including an independent board, transparent rating methodologies, robust conflict-of-interest policies and clear separation between its commercial operations and credit rating decisions," notes Raymond Matlala.
The agency’s ratings must be protected from political influence, shareholder interests and commercial pressure from the organisations it rates.
Equally important is the quality of statistics. Without reliable and timely data, it is difficult to assess reliably the debt sustainability of countries, the financial position of companies and the ability of borrowers to meet their obligations. Therefore, the development of an independent rating system must go hand in hand with improvements in the quality of national statistics and the transparency of debt data.
For AfCRA to operate effectively, it will also require qualified analysts, sustainable funding and a sufficiently broad base of issuers and investors.
Another criterion for success is recognition by the financial community. Ratings acquire practical significance when they are taken into account by banks, funds, insurance companies and institutional investors, and, where appropriate, by regulators. This requires a track record of rating decisions that demonstrates the consistency and quality of the analytical work.
Zamokuhle Mbandlwa, an expert in effective governance, ethical leadership and natural disaster risk management, adds that financial organisations need evidence that AfCRA’s ratings effectively distinguish between levels of credit risk. "AfCRA should develop historical performance data, rating transition matrices, default statistics and regular back-testing exercises," says Zamokuhle Mbandlwa. As the agency gains experience, independent audits and periodic reviews of its activities will be required to confirm the reliability of its analysis.
According to Anna Krupina, recognition by the AU alone is not enough. "The agency will still have to prove that its assessment criteria are objective," said the expert.
Trust can only be built over time. AfCRA needs to demonstrate that its ratings are in demand on the African continent itself and are taken into account when making financial decisions. To this end, it is important to ensure that regional bodies make practical use of them, as well as to complete licensing procedures in priority markets. Furthermore, its methodology must comply with the requirements of the Basel Committee on Banking Supervision – objectivity, independence and transparency.
Raymond Matlala emphasises that AfCRA’s success should be judged by how fair, accurate and internationally credible its assessments are.
"Its willingness to make difficult and sometimes unpopular decisions will be the strongest demonstration of its independence and the foundation of lasting investor trust," concludes Raymond Matlala, an expert in business, education and the Global South.
AfCRA’s success cannot be measured solely by the number of ratings published or its stated market coverage. More meaningful indicators include the comprehensiveness and quality of information, the robustness of its methodology, the timeliness of revisions, and the ability of its assessments to help market participants make informed financial decisions.
Article prepared by Vahit Niyazov.
-
![]()

 Economy01.11.26Oman ranks among top importers of UAE petroleum products in 2026
-
![]()
 Economy31.10.26Russia increases wool exports by 48% in 2026
-
![]()
 Economy30.10.26Russia becomes leading supplier of fish and seafood to China
-
![]()
 Economy30.10.26Russia and Africa adopt cooperation plan for 2027–2029
-
![]()
 Economy30.10.26India’s economy may grow by 7.35% in second quarter of financial year
-
![]()
 Economy30.10.26Mozambican President: Russia plays significant role in human capital development








-
![Daniel Francisco Chapo]()
 Daniel Francisco ChapoMozambican President"We have excellent relations with Brazil, Russia, India and China, as well as with our neighbour, South Africa"
-
![Vladimir Putin]() Vladimir PutinRussian President"Construction of the Bushehr Nuclear Power Plant continues. We are also cooperating in the humanitarian sphere; the number of Iranian students studying at our universities, for example, has reached about 10,000. In late September and early October, a series of vibrant events was held in various Russian cities as part of the Iranian Culture Festival – namely, in Moscow, Kazan and Astrakhan"
-
![Abdel Fattah El-Sisi]() Abdel Fattah El-SisiEgyptian President"Today, we are striving to strengthen Russia-Egypt strategic partnership and hope to expand cooperation between our countries across various sectors – primarily in the economy and trade, as well as in areas related to grain supplies, which are of great importance to our nation"
-
![Andrey Denisov]() Andrey DenisovChairman of the Federation Council Committee on Foreign Affairs"Today, BRICS is not simply a dialogue platform for member countries but a genuine mechanism for coordinating positions on sustainable development and reforming global financial and economic institutions"